What Buyers Need To Know About Homeowners Association Fees

 What Buyers Need To Know About Homeowners Association Fees Simplifying The Market
When buying a home, you’re probably thinking about mortgage rates, home prices, your down payment, and maybe even your closing costs. But you may not be thinking about homeowners association (HOA) fees. While you won’t necessarily have these, you should know it’s a possibility, depending on where you decide to live.

A homeowners association is basically an organization that oversees a housing community (including shared spaces) and sets and enforces rules for things like upkeep. Some buyers love the perks that come with an HOA, others may see the fees as an extra expense. The key is knowing what they cover and whether the benefits outweigh the costs for you.

The Benefits of Having an HOA

Think about this. If you’ve fallen in love with a home because of how beautiful the community is – maybe it’s the landscaping, the well-maintained streets, or the overall curb appeal – there’s a good chance the HOA is one of the reasons why it looks so good. Here are some of the biggest perks:

  • Neighborhood Maintenance: Many HOAs cover landscaping, snow removal, and upkeep of common areas. This helps maintain the neighborhood’s overall appearance.
  • Amenities: Depending on the neighborhood, an HOA could also include access to perks like a pool, clubhouse, fitness center, or even private security. In these cases, while you have to pay an HOA fee, you’re also saving money in some ways because you don’t need to have separate gym or pool memberships anymore.
  • Property Value Protection: Since HOAs enforce community standards, they prevent homes from falling into disrepair. So, you don’t have to worry about nearby eyesores hurting your property value.
  • Less Personal Upkeep: In some communities, HOAs even take care of exterior maintenance, roof repairs, or other shared responsibilities, reducing the work for homeowners.

HOA Fees: More Common, Especially in Newer Neighborhoods

Does every house have HOA fees? No, not all homes have them. But they are common, especially in newer communities. In fact, over 80% of newly built single-family homes are now part of an HOA, according to the Wall Street Journal (see graph below):
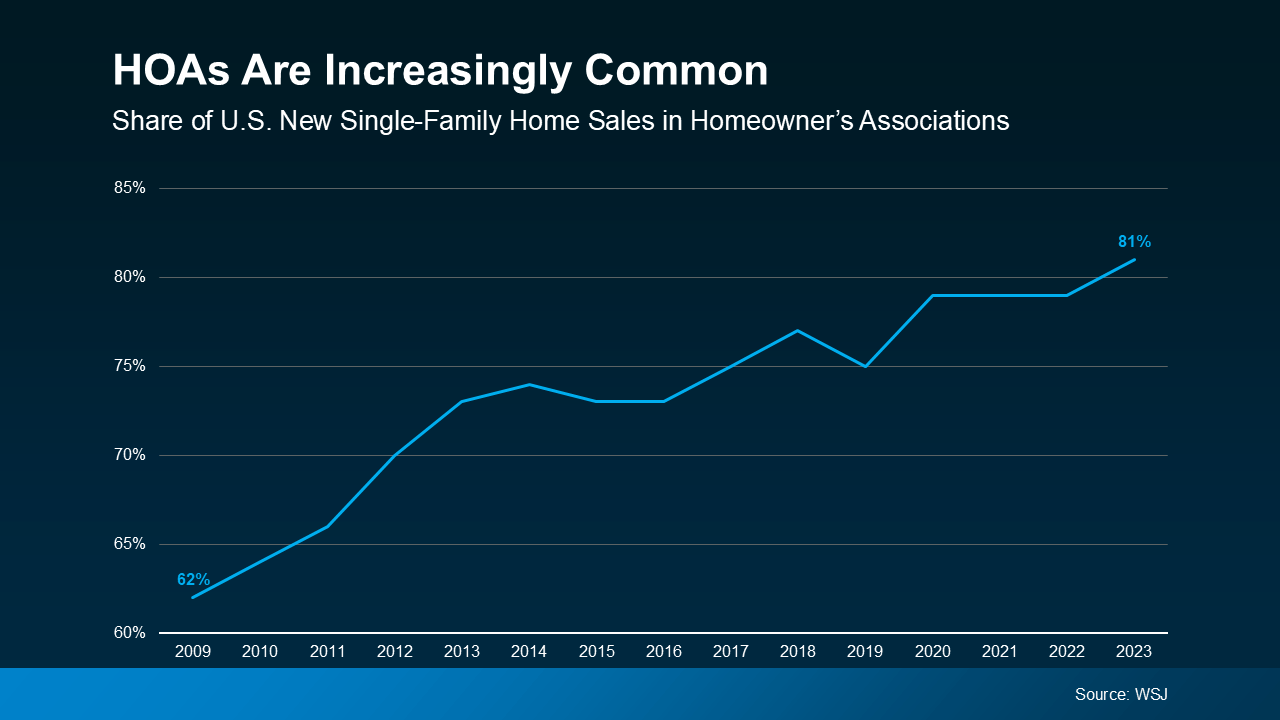
a graph with a line going upBut it’s not just new builds that have homeowners associations. Homes that were previously lived in may have an HOA fee too. According to Axios roughly 4 out of every 10 homes had an HOA in 2024.

HOA Fees and Your Home Search

Ask your agent about which homes do and do not have HOA fees as part of your search – and how much the fees are. Some neighborhoods have quarterly dues, some have monthly, some don’t have any at all. To give you some sort of baseline though, the median HOA fee rose last year to $125 per month, based on a report from Realtor.com.

But remember, the costs vary and sometimes these fees give you access to great perks. As Danielle Hale, Chief Economist at Realtor.com, explains:

“When considering a home with an HOA, buyers should work to understand what benefits it provides like maintenance, security, or communal amenities, and how the HOA fees factor into their overall budget.”

Bottom Line

Before buying a home in an HOA community, it’s a good idea to review the rules and fees so you know exactly what’s included, how that fits into your overall budget, and what restrictions may apply.

Would you rather pay an HOA fee for added perks, or skip it and have full control over your property? Connect with an agent to talk about what’s best for you.
Is It Better To Rent or Buy a Home?

Is It Better To Rent or Buy a Home? Simplifying The Market

You’ve probably asked yourself lately: Is it even worth trying to buy a home right now?

With high home prices and stubborn mortgage rates, renting can seem like the safer choice right now. Or maybe your only choice. That’s a very real feeling. And perhaps buying today isn’t your best move; it’s not for everyone right away. You should only buy a home when you’re ready and able to do it, and if the timing is right for you.

But here’s the thing you need to know about renting.

While it may feel like a safer bet today – and in some areas might even be less expensive month-to-month than owning – it can really cost you more over time.

In fact, a recent Bank of America survey found that 70% of aspiring homeowners worry about what long-term renting means for their future. And they’re not wrong.

Owning a home may seem way out of reach, but if you make a plan now and steadily work toward it, homeownership comes with serious long-term financial benefits.

Homeownership Builds Wealth Over Time

Buying a home isn’t just about having a place to live – it’s a step toward building your future wealth.

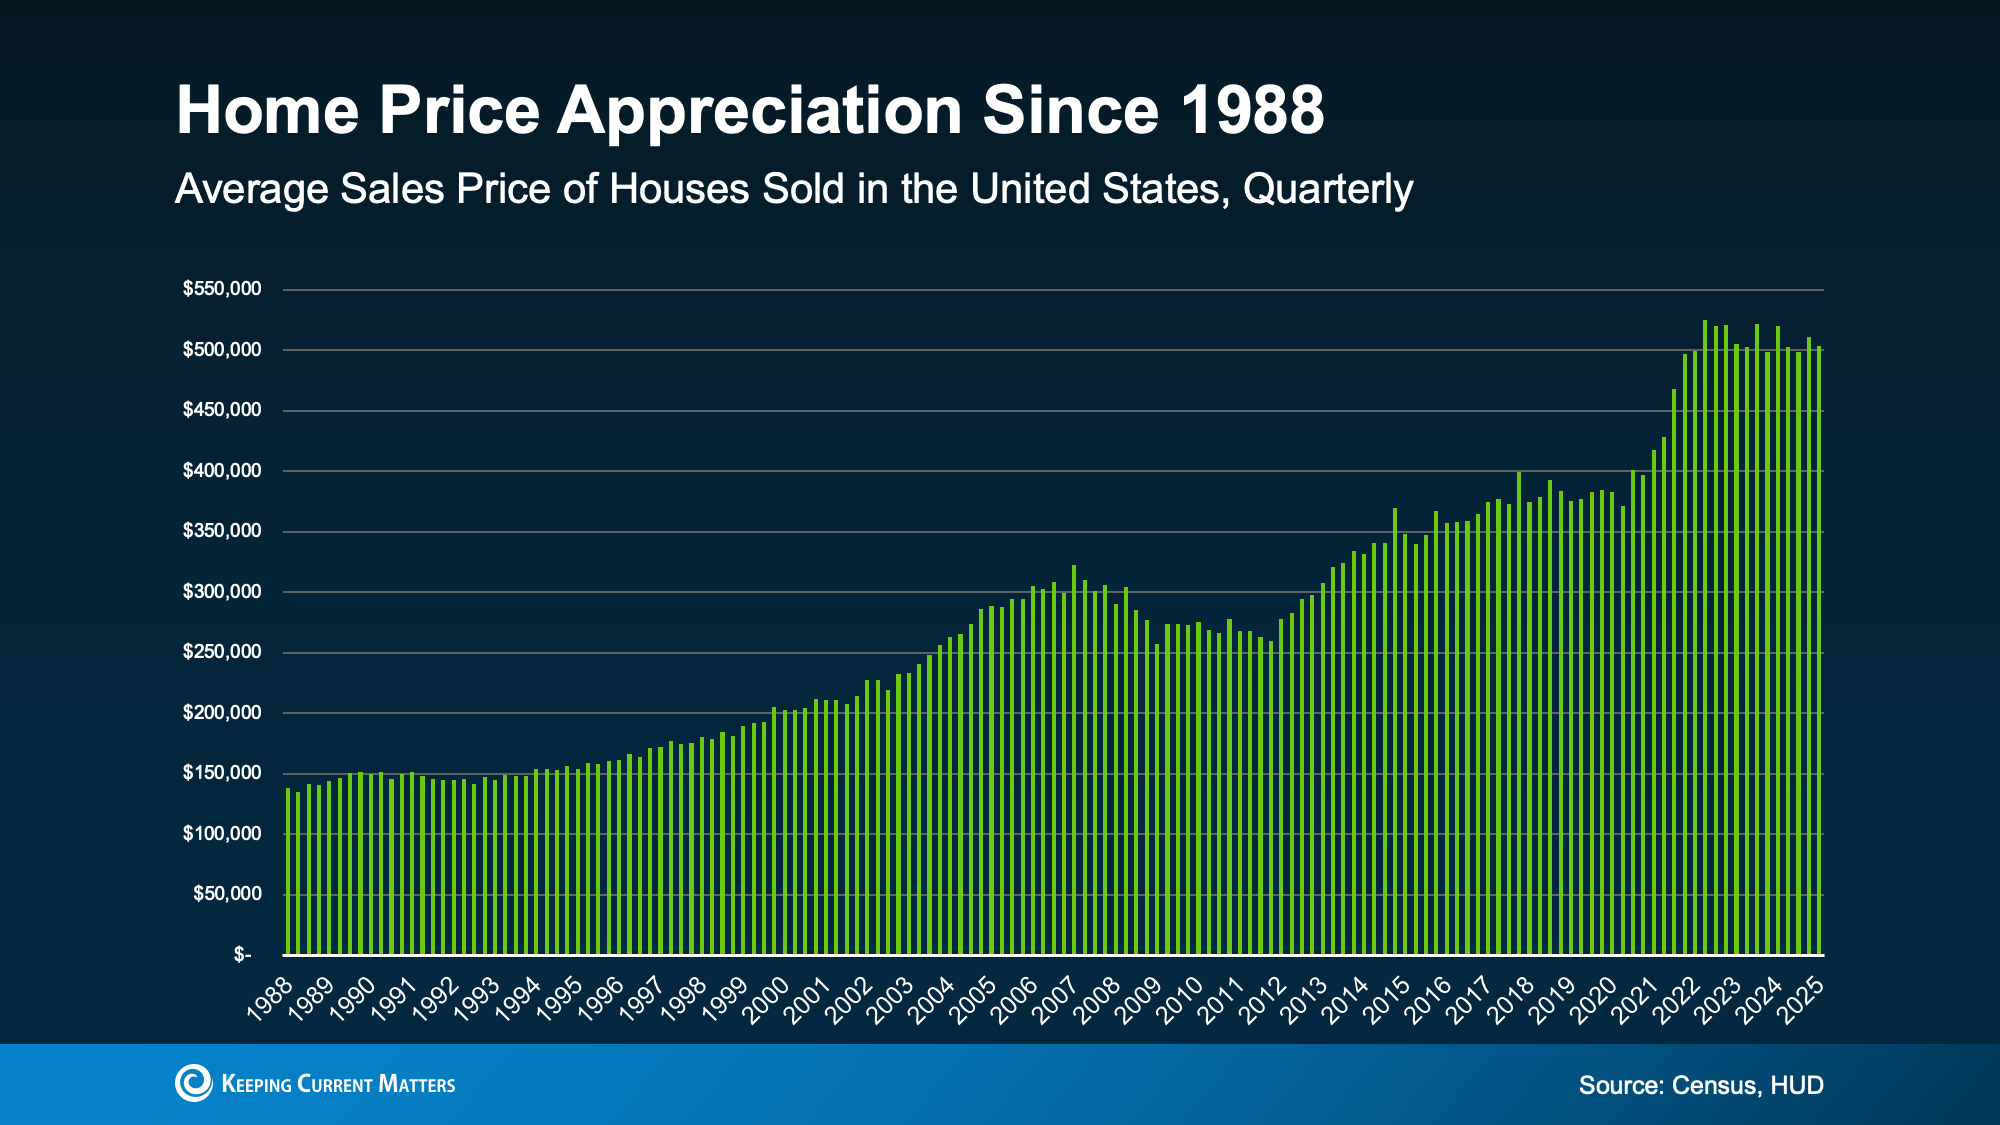
Why? Home prices typically rise over time, which means the longer you wait, the more expensive it is to buy. And even in some markets where home prices are softening today, the overall long-term trend speaks for itself (see graph below):

a graph of a price of houses sold in the united statesAnd as home values rise, so does your equity when you’re a homeowner. That’s the difference between what your home is worth and what you owe. So, with every mortgage payment, that equity grows. Over time, that becomes part of your net worth.

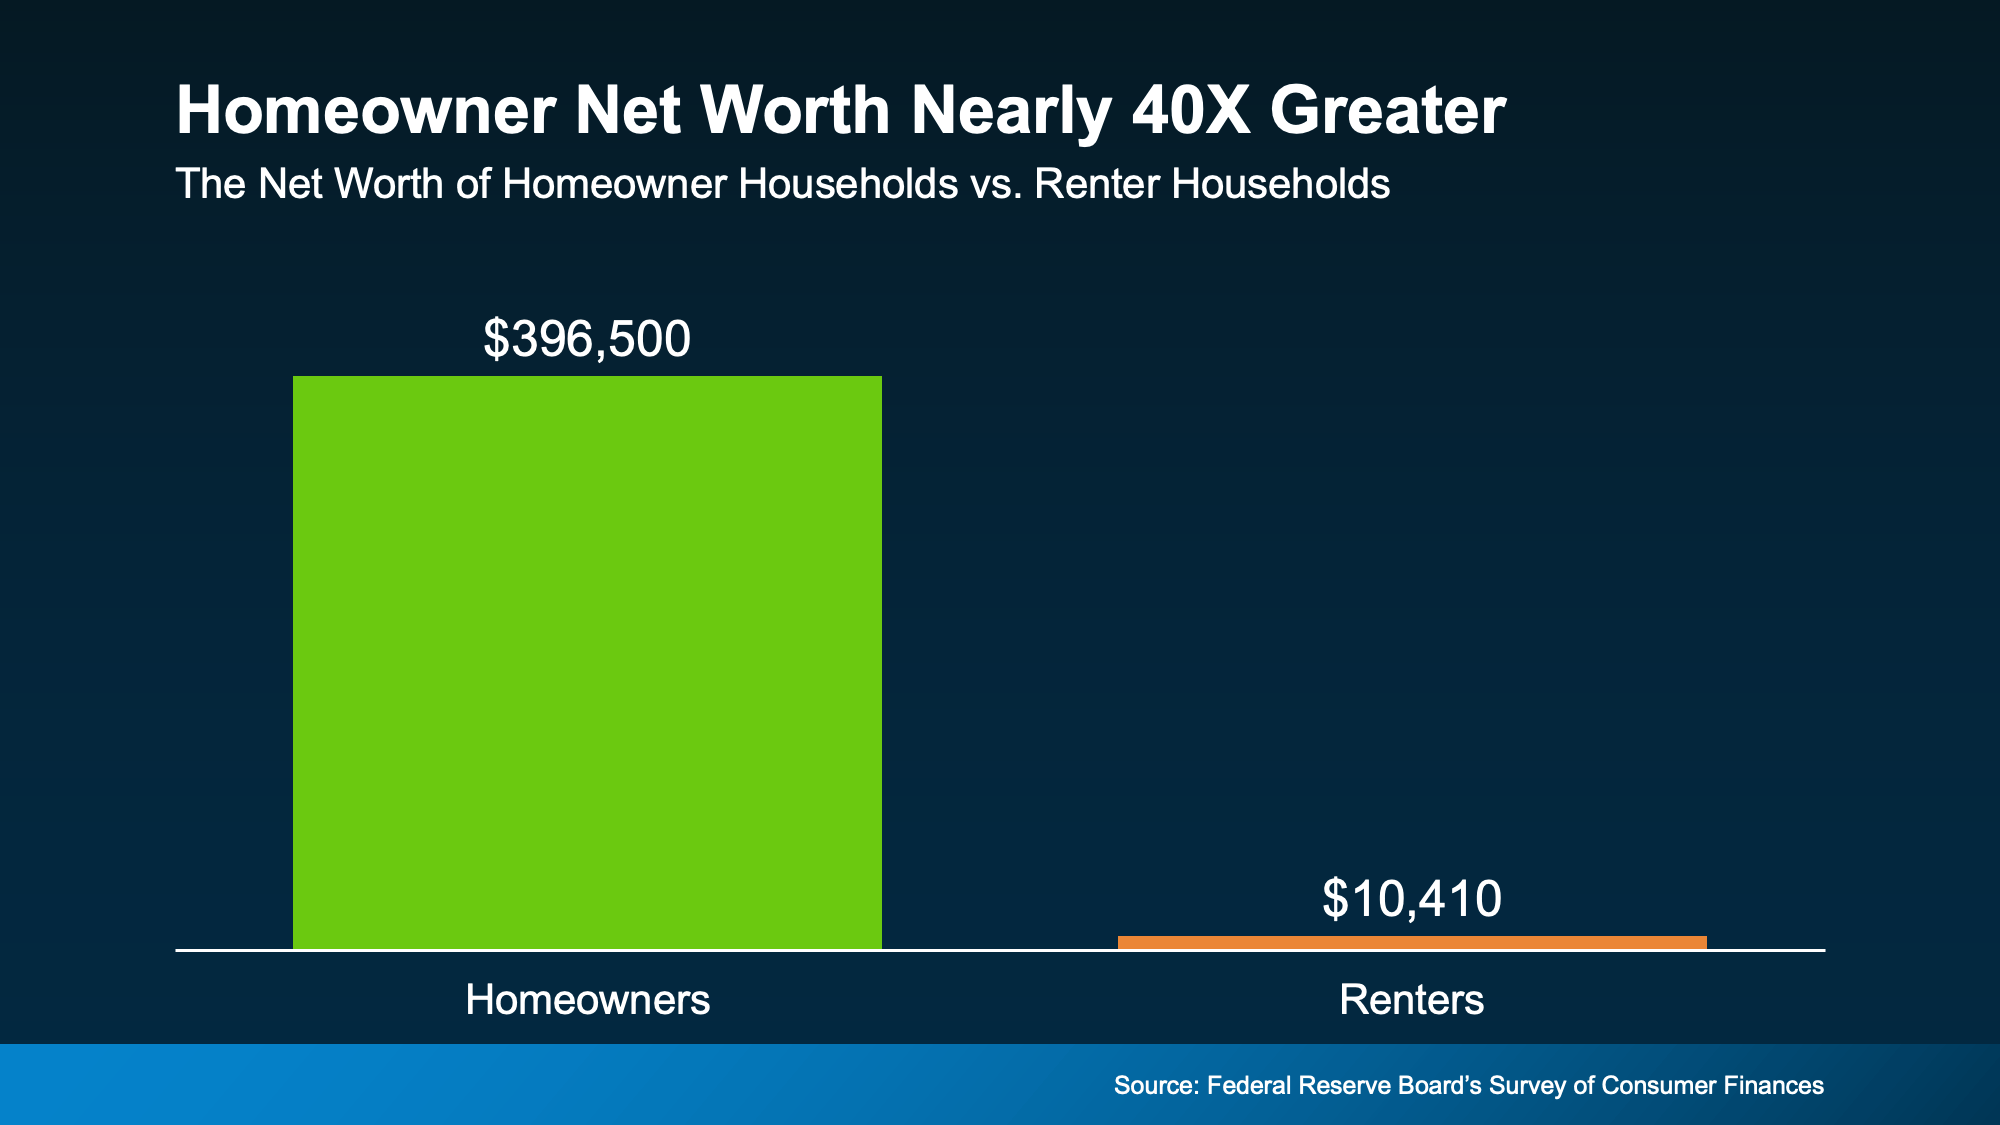
Today, the average homeowner’s net worth is nearly 40X greater than that of a renter. That’s a shocking difference, and the dollars in the visual below don’t lie (see graph below):

a green rectangle with white textAnd it’s one of the big reasons why Forbes says:

“While renting might seem like [the] less stressful option . . . owning a home is still a cornerstone of the American dream and a proven strategy for building long-term wealth.”

The Biggest Downside of Renting

So, short-term, why does renting feel like a simpler choice? Lower monthly payments, less responsibility, no strings attached. But long-term? It can sting.

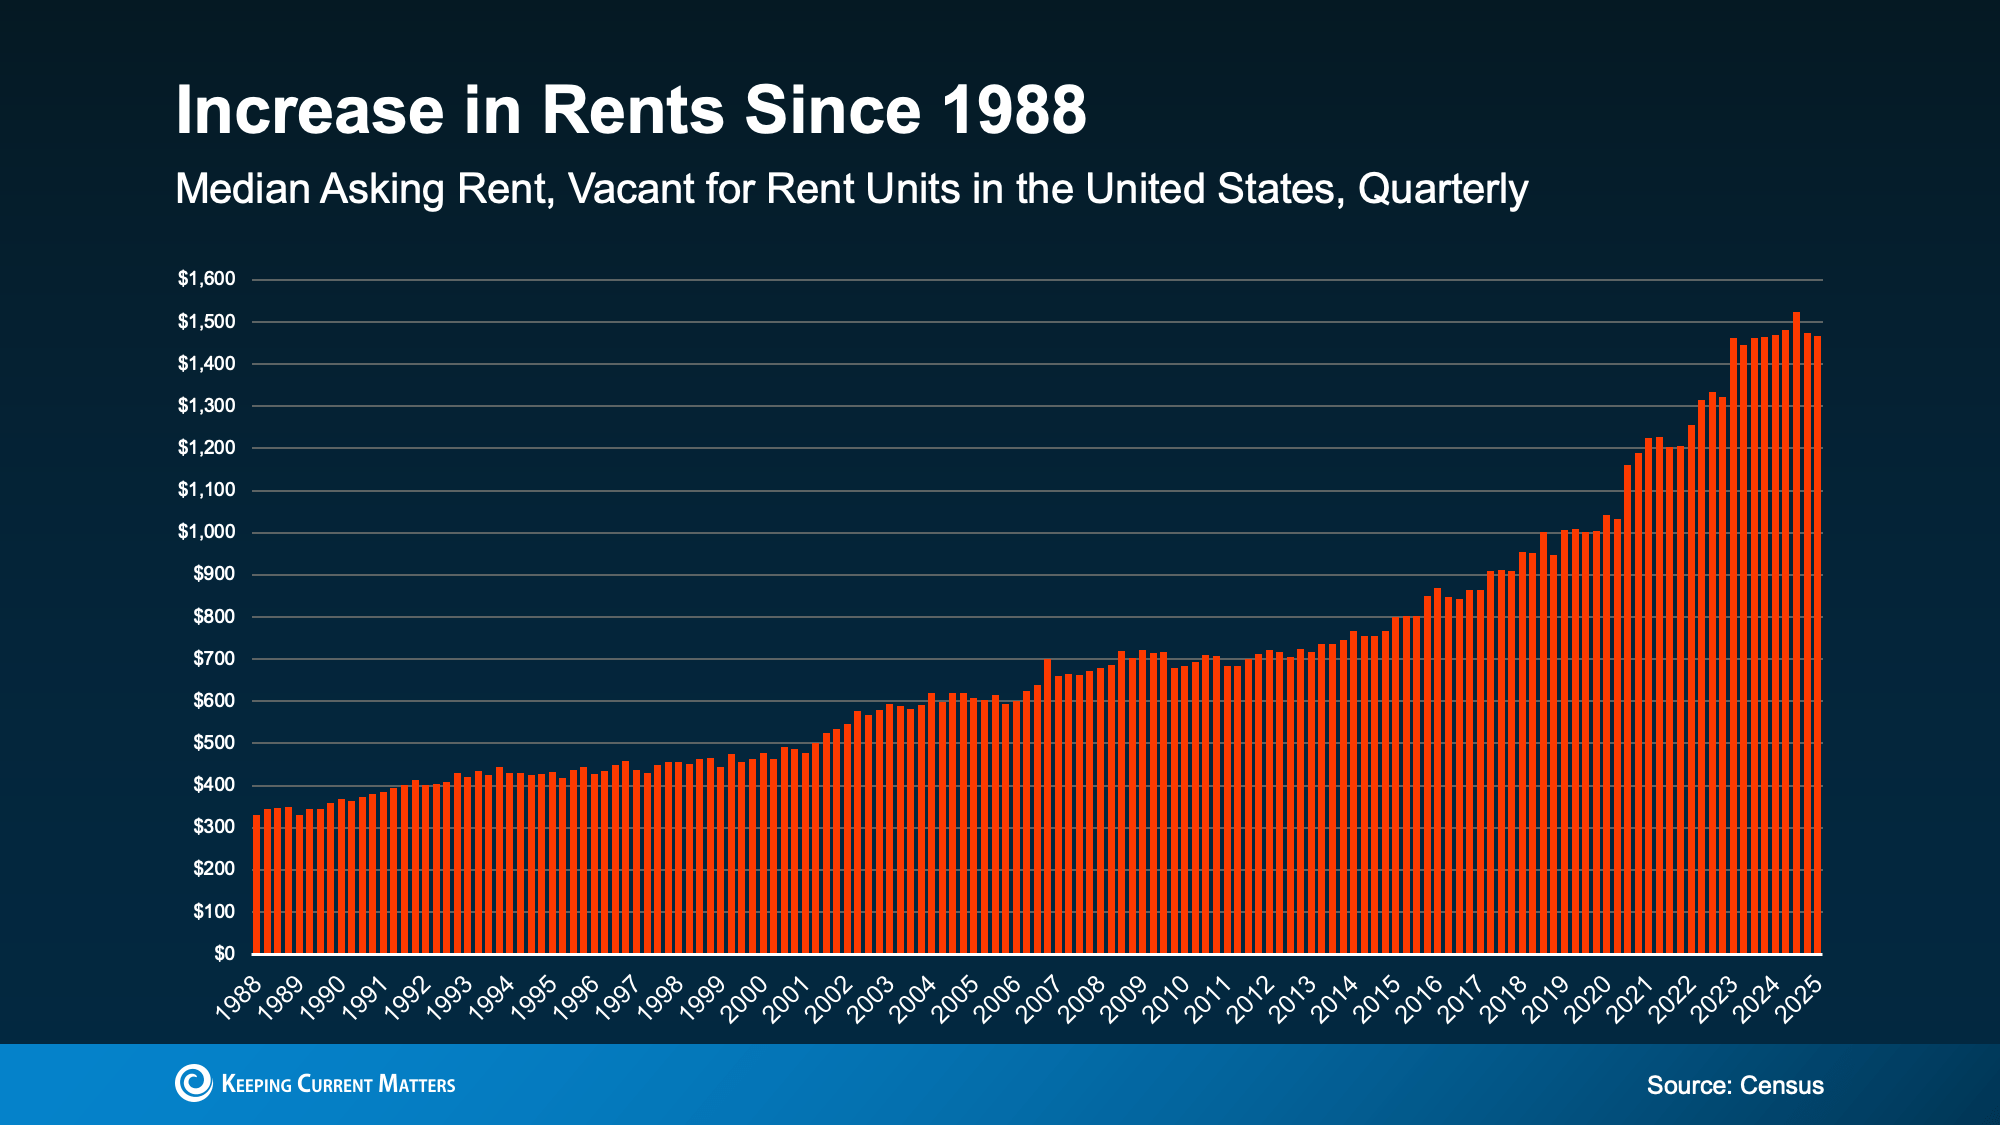
For decades, while home prices have been rising, rent has gone up too. And while rent has held rather steady more recently, history shows the overall trend is up and to the right. That makes saving for a home more complicated than ever (see graph below):

a graph of a number of peopleThat kind of financial uncertainty has a real impact. In the same Bank of America survey, 72% of potential buyers said they worry rising rent could affect their current and long-term finances.

Because rent doesn’t build wealth. It doesn’t come back to you later. It pays your landlord’s mortgage – not yours.

So, whether you rent or own, you’re paying a mortgage. The question is: whose mortgage do you want to pay?

Renting vs. Buying: What Really Matters

Think of it this way. Renting means your money is gone once you pay it. Owning means your payment builds equity – like a savings account you can live in. Sure, buying comes with responsibility. But it also comes with the kind of reward that grows over time. And that’s why you need a solid plan to get there.

As Joel Berner, Senior Economist at Realtor.com, explains:

“Households working on their budget will find it much easier to continue to rent than to go through the expenses of homeownership. However, they need to consider the equity and generational wealth they can build up by owning a home that they can’t by renting it. In the long run, buying a home may be a better investment even if the short-run costs seem prohibitive.”

Bottom Line

Renting may feel more do-able today. But over time, it could cost you more – without helping you build anything for your future.

If homeownership feels out of reach today, you’re not alone. And the first step toward getting out of the rental trap is to set a plan. Connect with an agent to set your specific goals and explore your options – so you’re ready when the time is right.

The Secret To Selling Your House in Today’s Market

The Secret To Selling Your House in Today’s Market Simplifying The Market

A few years ago, homes were flying off the shelves and getting multiple offers well over their asking price. It felt like you could name your price and still have buyers lined up at the door.

But today’s housing market is different. Buyers are getting more selective now that inventory has grown. Homes are sitting a little longer. And more sellers are having to cut their prices.

So, how do you still come out on top? It all starts with one thing, pricing your house right from the start. Today, that matters more than ever – and it can make or break your sale.

There’s a Real Price Disconnect Between Buyers and Sellers

A recent survey from Realtor.com shows 81% of home sellers believe they’ll get their asking price or more. But the actual sales data shows there’s a growing gap between what sellers expect and what buyers are actually willing to pay.

In fact, an annual report from the National Association of Realtors (NAR) shows 44% of recently sold homes went for less than the asking price. And 1 in 3 sellers had to cut their price at least once before the home sold. It’s a sign that expectations may be a little out of step with today’s reality.

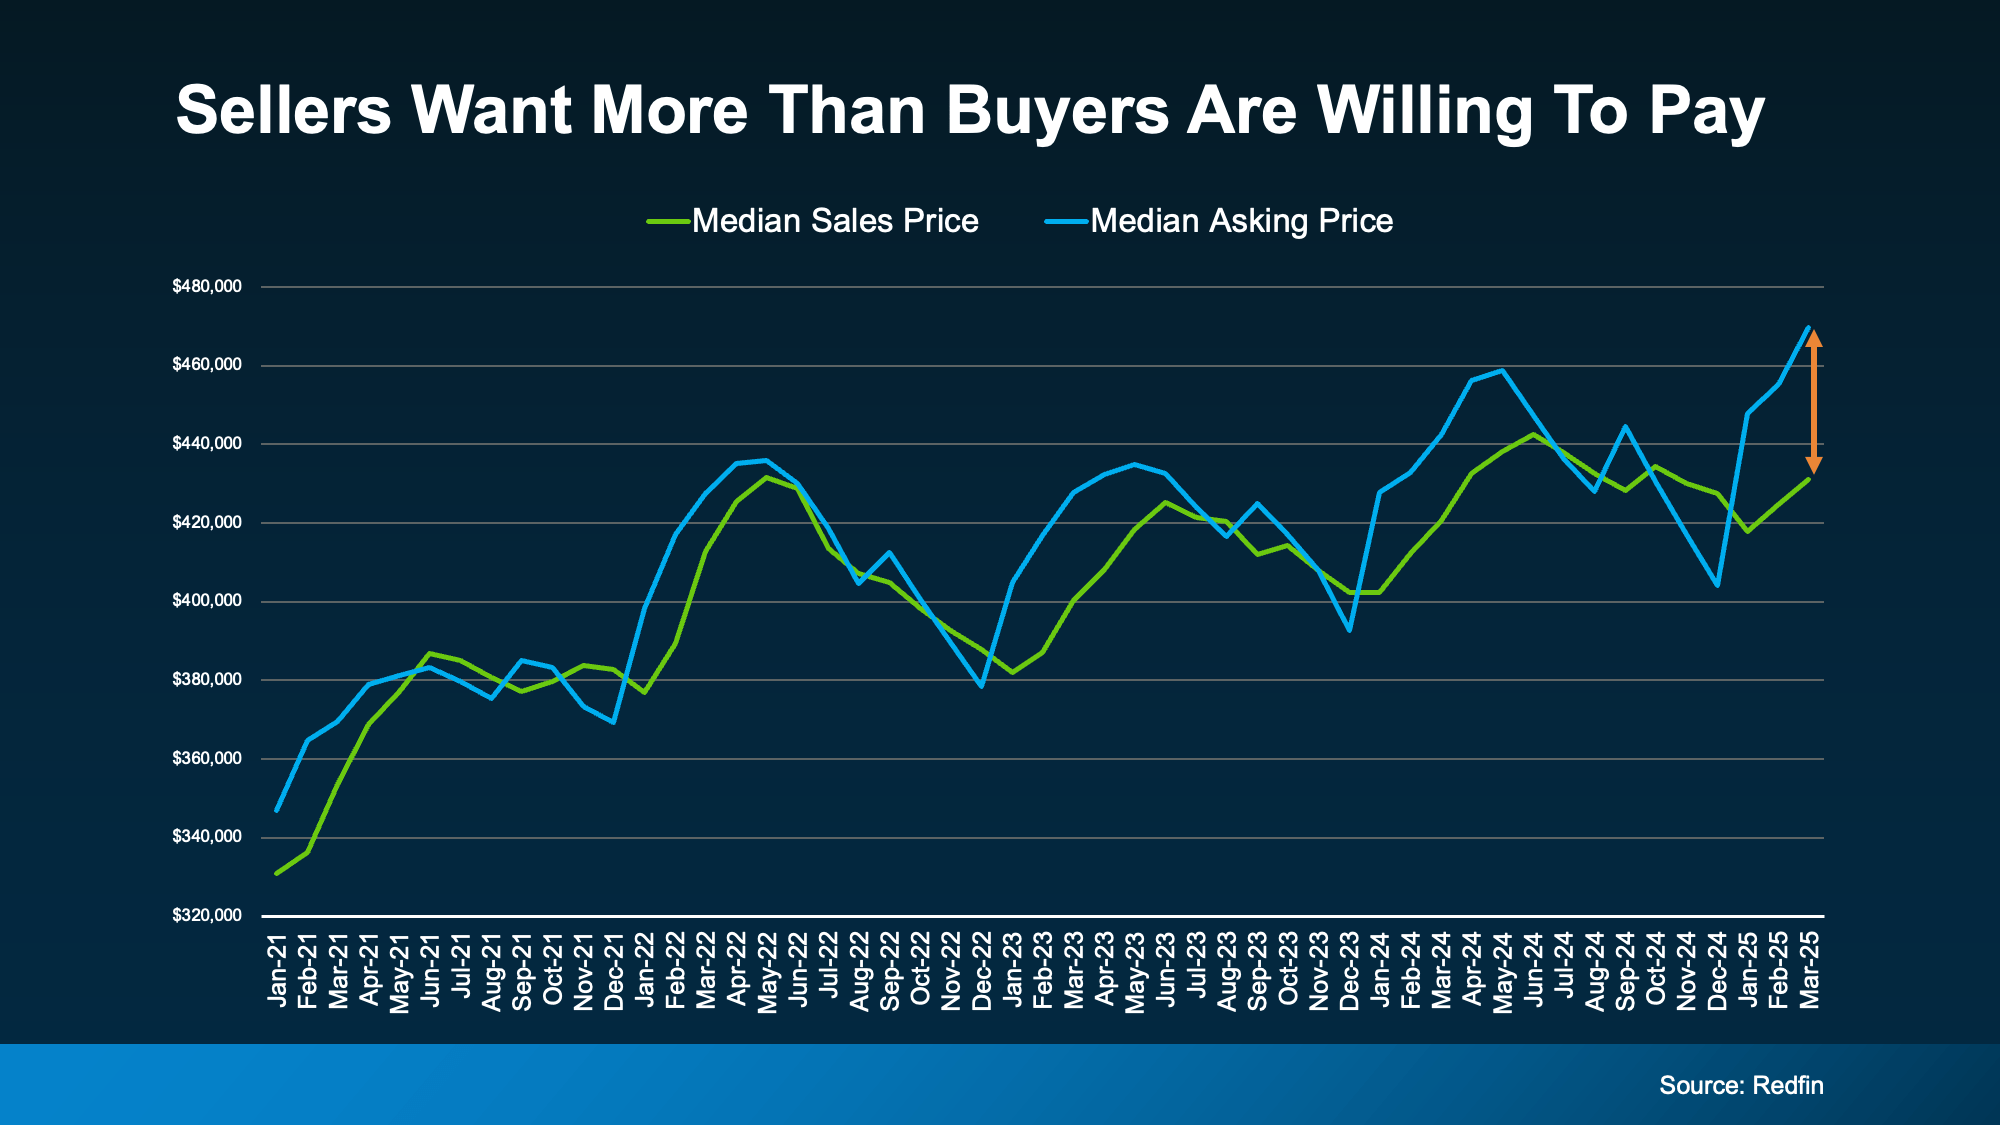
Check out the graph below. It uses data from Redfin to show that asking prices (blue line) are higher than actual sales prices (green line) by a wider and wider margin:

a graph of sales and pricesThis tells you something important: not all buyers are willing to pay what many sellers are asking. That doesn’t mean you can’t sell for a great price – but it does mean you need to start with a price that reflects what people are willing to pay in today’s market.

What Happens When You Overprice Your House?

Pricing your house high initially may seem like a smart move, so you have more room to negotiate. But the reality is, an overpriced home can sit on the market and turn buyers away. 

Buyers are smart. And when they see a house that’s been sitting for a while, they start to wonder what’s wrong with it. That can lead to fewer showings, less interest, and eventually, a price cut to re-ignite attention. As Realtor.com explains

“By getting the right price early on, you can increase the odds buyers will be interested in the home. In turn, this decreases the chances the home will sit on the market for a lengthier timeline, also reducing the odds you’ll need to lower the listing price.”

The longer a house sits, the harder it can be to sell.

You Still Have a Great Opportunity – If You Price Your House Right 

To avoid making this mistake, it’s important to lean on an agent who knows what’s happening locally when you set your asking price. 

Your agent will look at recent local sales, buyer trends, and inventory levels to find that pricing sweet spot for your neighborhood – because it’s going to be different based on where you live.

And here’s something else to keep in mind, home prices have climbed more than 57% over the past five years. So, even if you price a bit below the number you had your sights set on, you’ll likely still be in a great position profit-wise.

With a local real estate agent’s help, you’ll attract more attention, avoid seeing your house sit on the market too long, and maximize your chances of getting a strong offer.

In today’s market, the right price works. As Mike Simonsen, Founder of Altos Research, explains:

“. . . the best properties, well priced are selling quickly in most of the country.”

Bottom Line

The market has changed, but your opportunity to sell hasn’t. You just need the right pricing plan. Talk to a local real estate agent to go over what’s happening with prices in your area and determine what price would help your house sell quickly and for top dollar.

Paused Your Moving Plans? Here’s Why It’s Time To Hit Play Again

Paused Your Moving Plans? Here’s Why It’s Time To Hit Play Again Simplifying The Market

It’s not really a surprise that 70% of buyers paused their home search last year. Maybe you were one of them. And if so, no judgment. Conditions just weren’t great.

Inventory was too low, prices were too high, and mortgage rates were bouncing all over. That made it really hard to find a home you loved – and could afford. And why sell if you’re not sure where you’re going to go?

But here’s the thing: the market’s shifting. And it might be time to hit play again.

The Inventory Sweet Spot

More homeowners are jumping back into their search to make a move this year. Builders are finishing more homes. And together, that’s creating more options for you when you move – maybe even the home you’ve been waiting for.

More homes = more possibilities.

But there’s more to it than that. When you sell, you don’t want to feel like it’s impossible to find your next home. At the same time, you also don’t want inventory to be so high, it takes ages for your house to sell. Right now, you’ll get the best of both worlds.

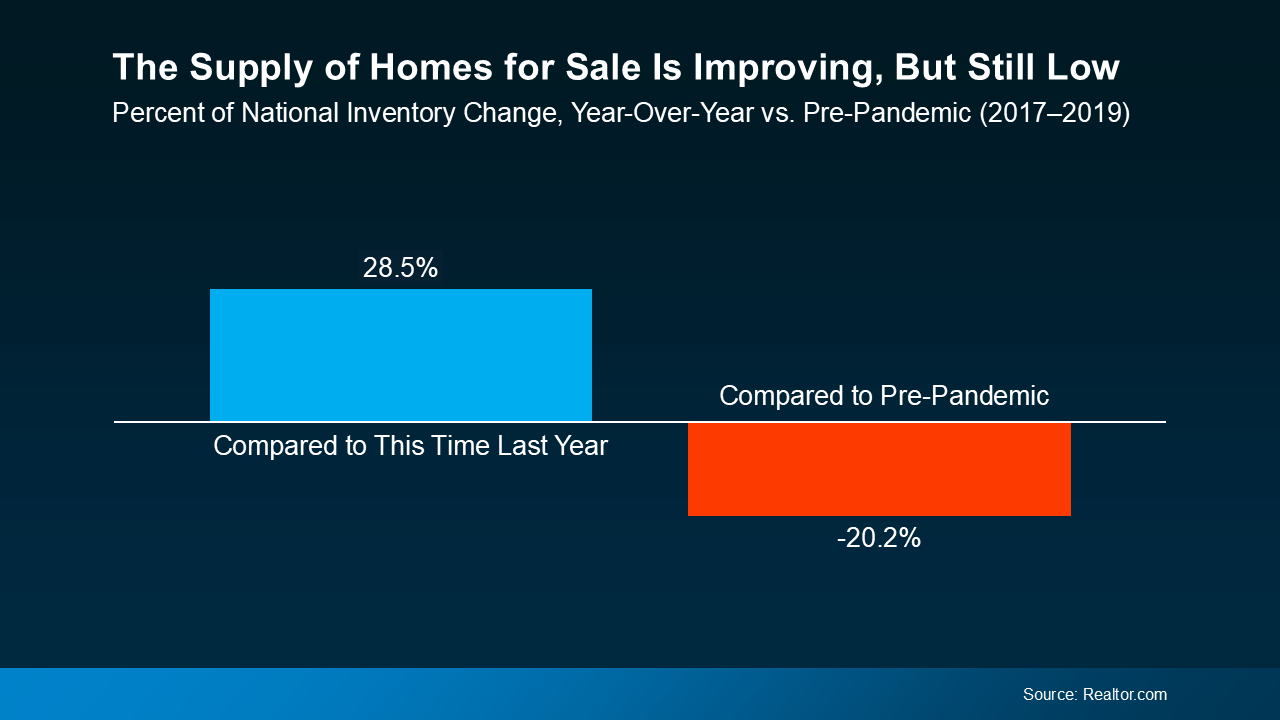
This data will help paint the picture for you. According to Realtor.com, inventory has jumped 28.5% since this time last year, but it’s still below pre-pandemic levels in most markets – and here’s why this is such a sweet spot (see graph below):

a graph of sales and pricesBasically, there are more homes to choose from when you make your move, but not so many that you’ll struggle to sell your current house. Your home should sell quickly if you work with an agent to make sure it’s priced right and prepped to impress.

More options. Less chaos. Solid demand: That’s the real sweet spot.

But here’s something else to consider. Data from Realtor.com also shows inventory has been on the rise for 17 straight months. And experts agree it’s likely to continue climbing throughout the year. As Lance Lambert, Co-Founder of ResiClub explains:

“The fact that inventory is rising year-over-year . . . strongly suggests that national active housing inventory for sale is likely to end the year higher.​”

So, this may actually be the best time to sell. Your house may stand out more now than it would as the year goes on and inventory grows even more. Wait too long, and you may be one of many trying to stand out later this year.

Bottom Line

If you’ve been waiting for the housing market to give you a sign – it just did. Whether you’re looking to move up, scale down, or relocate completely, this might be the best balance we’ve seen in a while.

What’s holding you back from taking advantage of this sweet spot? Connect with an agent to talk through it and see what’s possible.

You Finally Have More Options for Your Move

You Finally Have More Options for Your Move Simplifying The Market

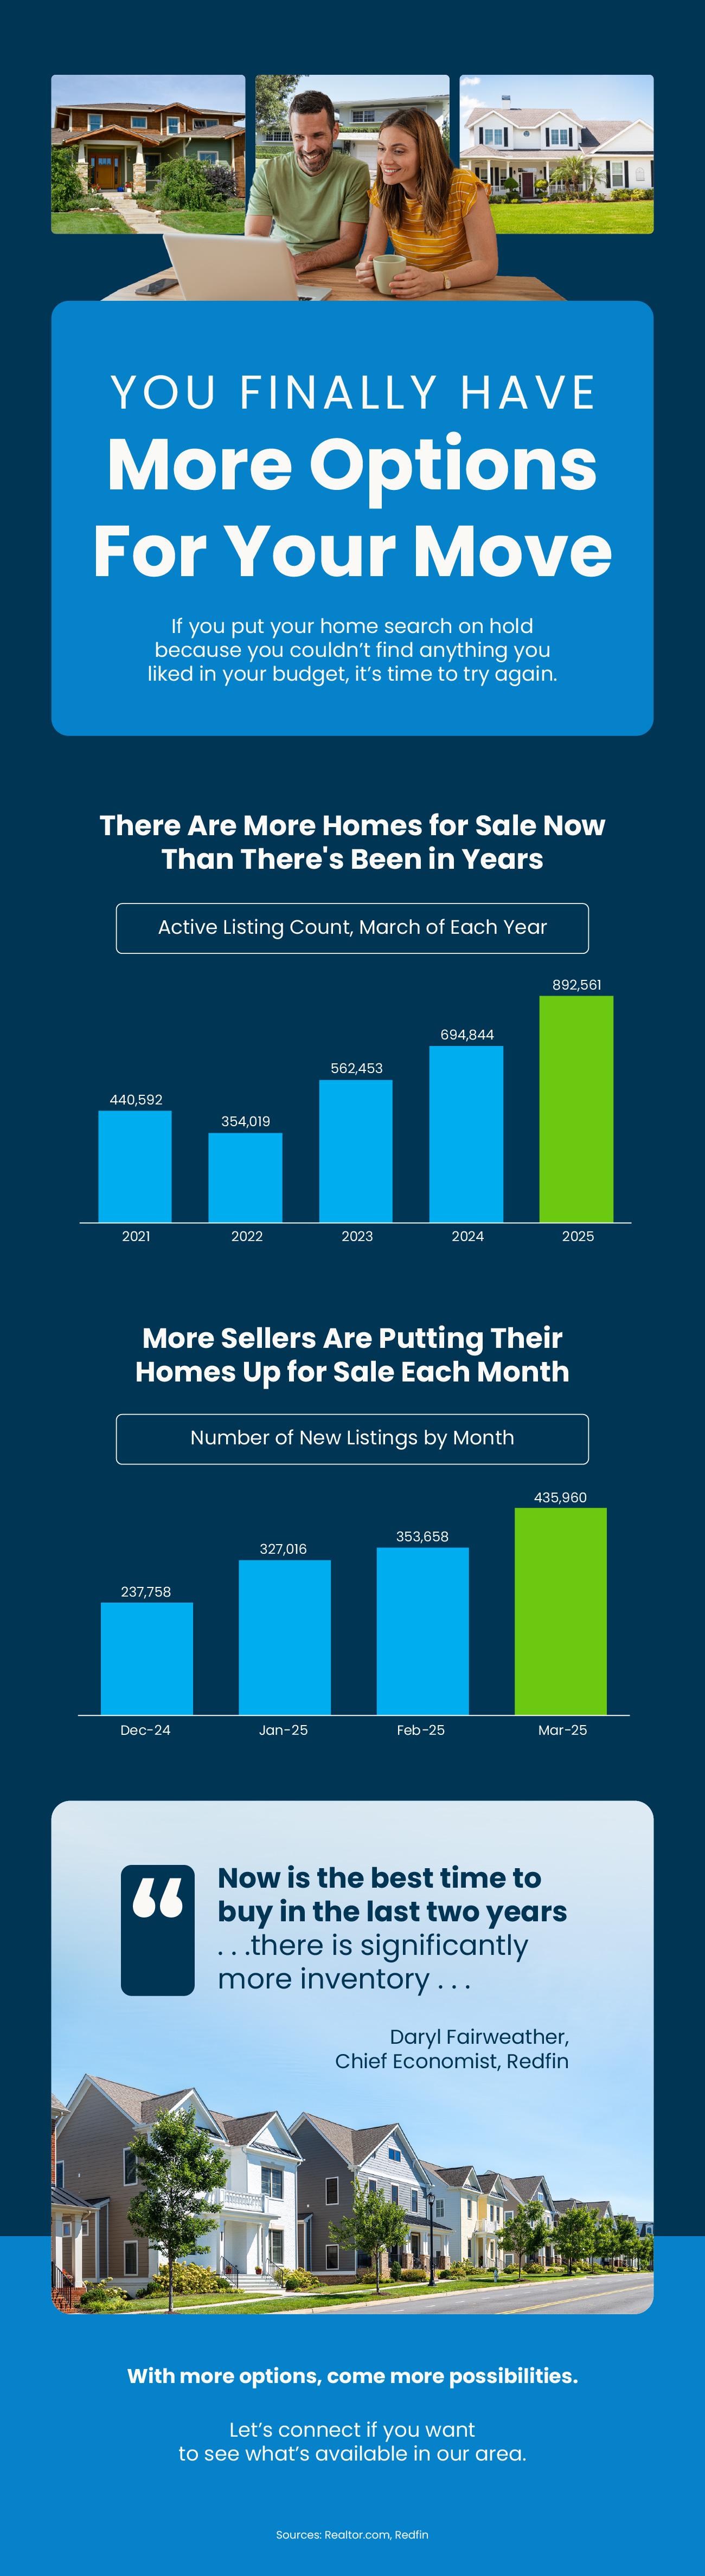
a screenshot of a graph

Some Highlights

  • If you put your home search on hold because you couldn’t find anything you liked in your budget, it’s time to try again. ​
  • There’s a much wider selection of homes for sale, with more fresh listings hitting the market each month.
  • With more options come more possibilities. Connect with an agent if you want to see what’s available in your area.​

Should I Buy a Home Now or Wait?

Should I Buy a Home Now or Wait? Simplifying The Market

At some point, you’ve probably heard the saying: “Yesterday was the best time to buy a home, but the next best time is today.”

That’s because homeownership is about the long game – and home prices typically rise over time. So, while you may be holding out for prices to fall or rates to improve, you should know that trying to time the market rarely works.

Here’s what most buyers don’t always think about: the longer you wait, the more buying could cost you. And you deserve to understand why.

Forecasts Say Prices Will Keep Climbing

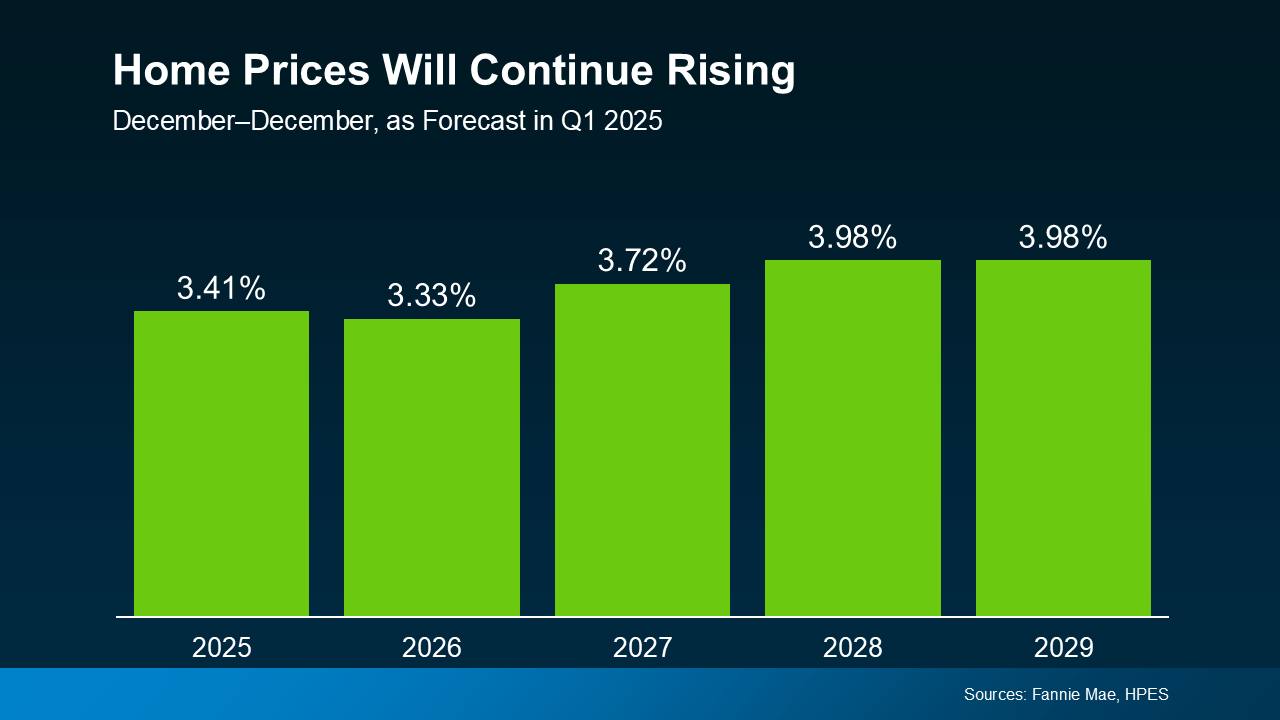
Each quarter, over 100 housing market experts weigh in for the Home Price Expectations Survey from Fannie Mae, and they consistently agree on one thing: nationally, home prices are expected to rise through at least 2029.

Yes, the sharp price increases are behind us, but experts project a steady, healthy, and sustainable increase of 3-4% per year going forward. And while this will vary by local market from year to year, the good news is, this is a much more normal pace – a welcome sign for the housing market and hopeful buyers (see graph below):

a graph of green bars

And even in markets experiencing more modest price growth or slight short-term declines, the long game of homeownership wins over time.

So, here’s what to keep in mind:

  • Next year’s home prices will be higher than this year’s. The longer you wait, the more the purchase price will go up.
  • Waiting for the perfect mortgage rate or a price drop may backfire. Even if rates dip slightly, projected home price growth could still make waiting more expensive overall.
  • Buying now means building equity sooner. When you play the long game of homeownership, your equity rewards you over time.

What You’ll Miss Out On

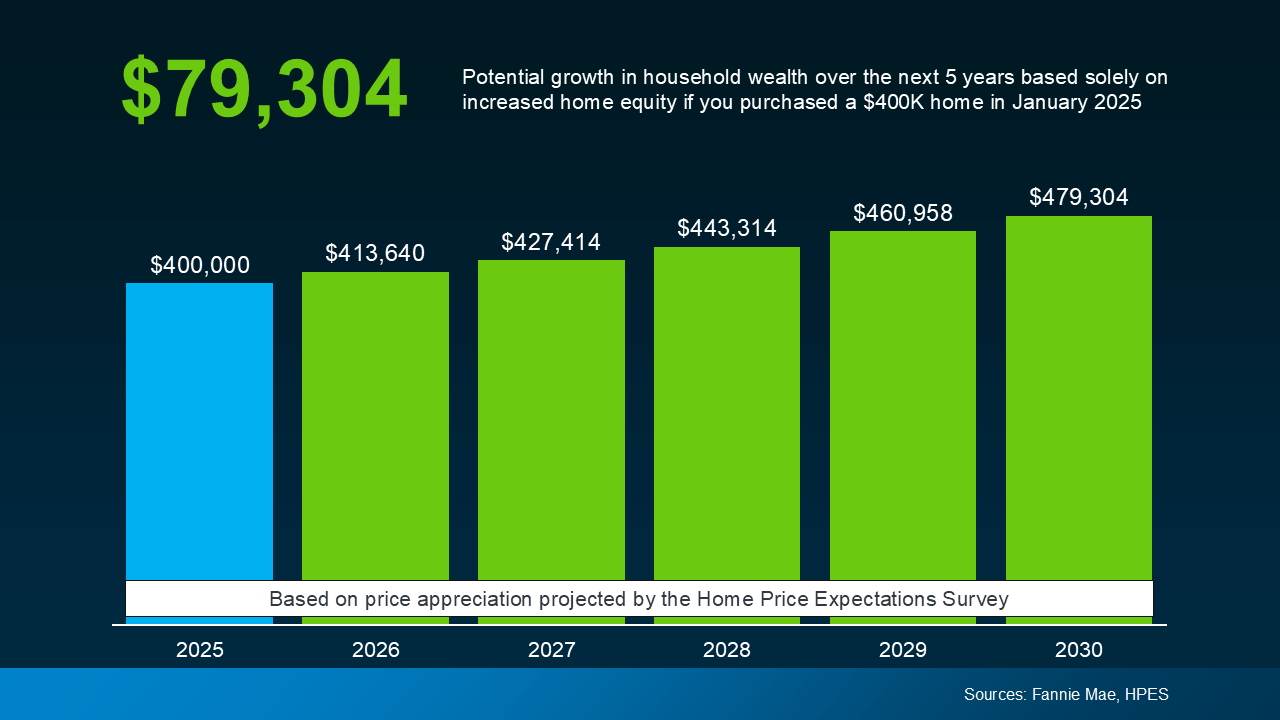
Let’s put real numbers into this equation, because it adds up quickly. Based on those expert projections, if you bought a typical $400,000 home in 2025, it could gain nearly $80,000 in value by 2030 (see graph below):

a graph of growth in a chartThat’s a serious boost to your future wealth – and why your friends and family who already bought a home are so glad they did. Time in the market matters.

So, the question isn’t: should I wait? It’s really: can I afford to buy now? Because if you can stretch a little or you’re willing to buy something a bit smaller just to get your foot in the door, this is why it’ll be worth it.

Yes, today’s housing market has challenges, but there are ways to make it work, like exploring different neighborhoods, asking your lender about alternative financing, or tapping into down payment assistance programs.

The key is making a move when it makes sense for you, rather than waiting for a perfect scenario that may never arrive.

Bottom Line

Time in the Market Beats Timing the Market.

If you’re debating whether to buy now or wait, remember this: real estate rewards those who get in the market, not those who try to time it perfectly.

Want to take a look at what’s happening with prices in your local area? Whether you’re ready to buy now or just exploring your options, having a plan in place can set you up for long-term success.

What’s Your House Worth Now? The Answer May Surprise You

What’s Your House Worth Now? The Answer May Surprise You Simplifying The Market

Let’s talk about something you might not check nearly as often as your bank account – and that’s how much your home is worth. But when it comes to your financial situation, it’s an important thing to remember. When’s the last time you had a professional show you the value of your home?

Think about it. For most people, your house is probably the biggest asset you have. And if you’ve owned your home for a few years (or longer), chances are it’s been quietly building wealth for you in the background. And honestly? You might be surprised by just how much. 

What Is Home Equity?

This wealth you may not even realize you have comes in the form of home equity. Home equity is the difference between what your house is worth and what you still owe on your mortgage. It grows over time as home values rise and as you pay down your mortgage each month. Here’s an example to help you really understand how this works.

Let’s say your house is now worth $500,000, and you have $200,000 left to pay off on your loan. That means you have $300,000 in equity. And most homeowners are sitting on some pretty significant equity right now.

According to Cotality (formerly CoreLogic), the average homeowner with a mortgage has about $311,000 in equity.

Why You Probably Have More Than You Think

Here are the two main reasons homeowners like you have record amounts of equity right now:

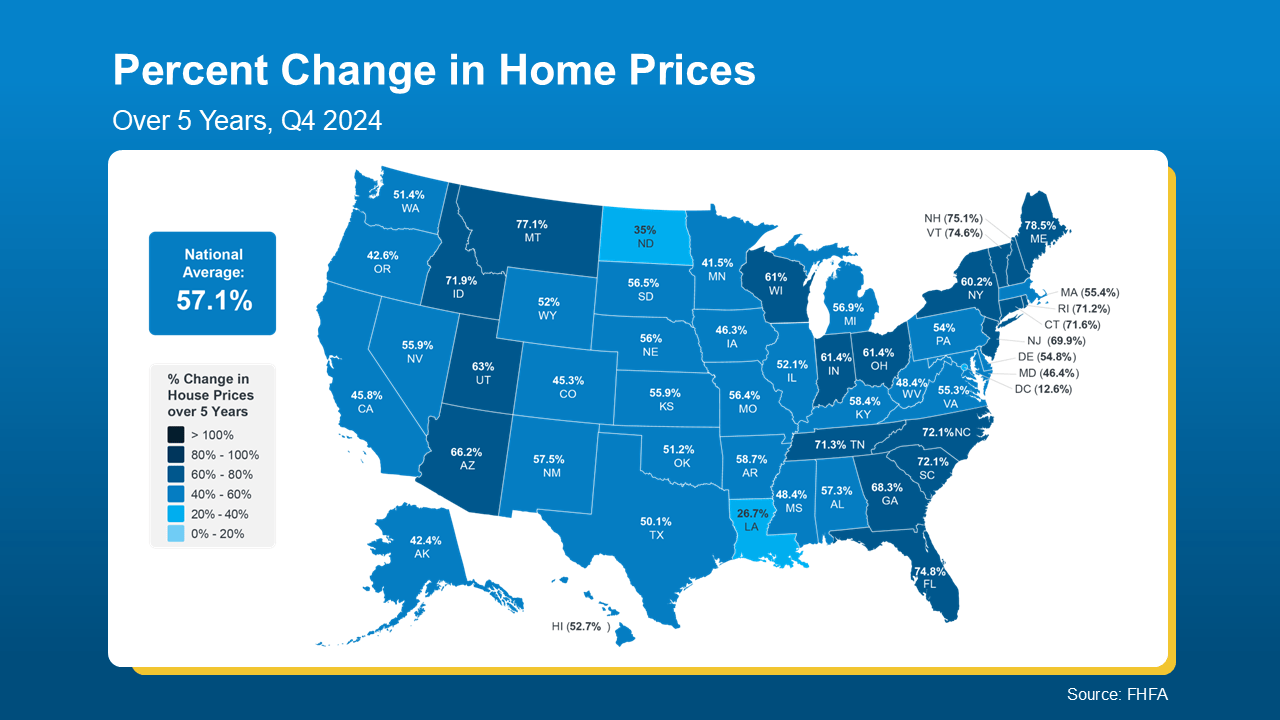
1. Significant Home Price Growth. According to the Federal Housing Finance Agency (FHFA), home prices have jumped by more than 57% nationwide over the last five years (see map below):

a map of the united statesAnd if you purchased your home a few years ago (or more), this means your house is likely worth much more now than when you first bought it, thanks to how much prices have climbed lately.

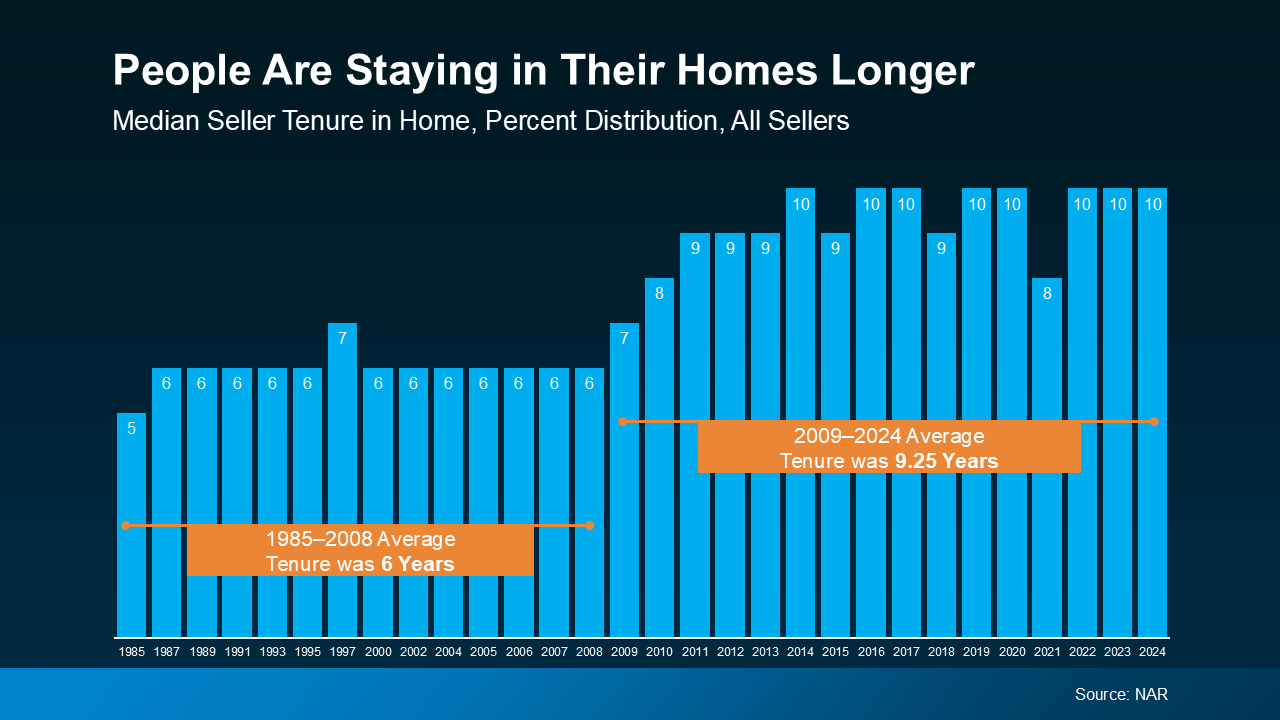
2. People Are Living in Their Homes Longer. Data from the National Association of Realtors (NAR), shows the average homeowner stays in their home for about 10 years now (see graph below):

a graph of blue bars with orange textThat’s longer than it used to be. And over that decade? You’ve built equity just by making your mortgage payments and riding the wave of rising home values.

So, if you’re one of those people who’s been in their home for that long, here’s how much the behind-the-scenes price growth has helped you out. According to NAR:

“Over the past decade, the typical homeowner has accumulated $201,600 in wealth solely from price appreciation.”

What Could You Actually Do with That Equity?

Remember, your house might be your biggest financial asset – and, if you’re smart about how you leverage your equity, it could open up some exciting opportunities for your future.

  • Use it to help buy your next home. Your equity could help you cover the down payment on your next home. In some cases, it might even mean you can buy your next house in all cash.
  • Renovate your current house to better suit your life now. And, if you’re strategic about your projects, they could add even more value to your home if you do sell later on.
  • Start the business you’ve always dreamed of. Your equity could be exactly what you need for startup costs, equipment, or marketing. And that could help increase your earning potential, so you’re getting yet another financial boost.

Bottom Line

Chances are, your house is worth a lot more than you realize. Whether you’re thinking about selling, upgrading, or simply want to understand your options, your equity isn’t just a number. It’s a tool.

If you sold your house and had significant equity to work with, what would you do with it? Connect with an agent to figure out how to turn your home’s value into your next big move.

What You Can Do When Mortgage Rates Are a Moving Target

What You Can Do When Mortgage Rates Are a Moving Target Simplifying The Market

Have you seen where mortgage rates have been lately? One day they go down a little. The next day, they go back up again. It can feel confusing and even frustrating if you’re trying to decide whether now’s a good time to buy a home.

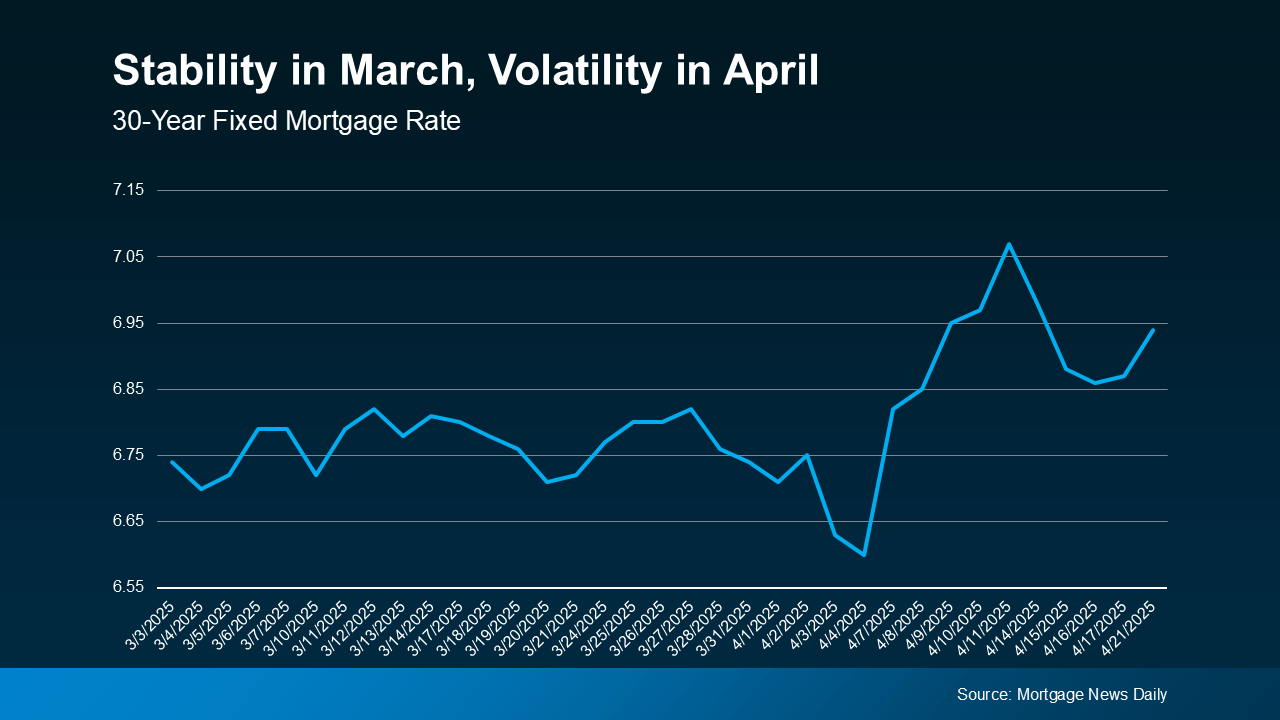
Take a look at the graph below. It uses data from Mortgage News Daily to show that after a relatively stable month of March, mortgage rates have been on a bit of a roller coaster ride in April:

This kind of up-and-down volatility is expected when economic changes are happening.
And that’s one of the reasons why trying to time the market isn’t your best move. You can’t control what happens with mortgage rates. But you’re not powerless. Even with all the economic uncertainty right now, there are things you can do.

You can control your credit score, loan type, and loan term. That way, you can get the best rate possible in today’s market.

Your Credit Score

Your credit score can really affect the mortgage rate you qualify for. Even a small change in your score can make a big difference in your monthly payment. Like Bankrate says:

“Your credit score is one of the most important factors lenders consider when you apply for a mortgage. Not just to qualify for the loan itself, but for the conditions: Typically, the higher your score, the lower the interest rates and better terms you’ll qualify for.”

Keeping your credit score up is key when it comes to qualifying for a home loan. If you’re not sure where your score stands or how to improve it, talk to a loan officer you trust.

Your Loan Type

There are also different types of loans out there, and each one comes with unique requirements for qualified buyers. The Consumer Financial Protection Bureau (CFPB) explains:

“There are several broad categories of mortgage loans, such as conventional, FHA, USDA, and VA loans. Lenders decide which products to offer, and loan types have different eligibility requirements. Rates can be significantly different depending on what loan type you choose. Talking to multiple lenders can help you better understand all of the options available to you.

Always work with a mortgage professional to figure out which loan makes the most sense for you and your financial situation.

Your Loan Term

Just like there are different loan types, there are also different loan terms. Freddie Mac puts it like this:

“When choosing the right home loan for you, it’s important to consider the loan term, which is the length of time it will take you to repay your loan before you fully own your home. Your loan term will affect your interest rate, monthly payment, and the total amount of interest you will pay over the life of the loan.

Most lenders typically offer 15, 20, or 30-year conventional loans. Be sure to ask your loan officer what’s best for you.

Bottom Line

You can’t control what’s happening with the economy or mortgage rates, but you can take steps that’ll help you get the best rate possible.

Connect with a local real estate agent and a lender to talk about what you can do today to put yourself in a strong spot for when you’re ready to buy a home.

Don’t Miss This Prime Spring Window To Sell Your House

Don’t Miss This Prime Spring Window To Sell Your House Simplifying The Market

According to Realtor.com, the best week to list your house this year was April 13–19. And since that week has come and gone, you might be wondering: did I miss my chance? Not at all – and here’s why.

That’s just one source’s take, based on their own research. Other organizations run similar studies. And since different places use different methodologies for their research, sometimes the results vary too – and that’s actually good news for you. According to Zillow, the best time to list your house is still ahead.

The latest research from Zillow says sellers who list their homes in late May tend to see higher sale prices based on home sales from last year. The study explains why:

“Search activity typically peaks before Memorial Day, as shoppers get serious about house hunting before their summer vacation and the new school year in the fall. By targeting late spring, sellers can get their home listed when the most shoppers are looking. When more buyers are competing for homes, sellers can command a higher price.

And they’re not the only ones saying selling in May can help homeowners net top dollar. ATTOM Data conducted a similar study by analyzing 59 million home sales over the past 13 years:

Freshly compiled sales statistics from ATTOM demonstrate that home sellers continue to reap significant benefits from listing their properties during the month of May. Examination of home sales trends spanning thirteen years reveals that, on average, sellers are commanding 11.1 percent premium above the estimated market value.”

An article from Bankrate echoes this sentiment and brings this all together to show that any time in April or May is a good time:

“Some patterns and trends usually do hold true throughout the year, and one is that spring continues to be the best time to sell. Sellers can net thousands of dollars more if they sell during the peak months of April and May. . .”

The window to sell during prime time is very much still open, so you can make a move and potentially cash in big if you sell now.

That said, the best week to list your house really depends on a few local factors, like buyer demand, how many homes are for sale nearby, and how quickly things are selling. That’s why working with an experienced agent who knows your area is key. 

Bottom Line

Spring is the busiest time in real estate – and there’s still time to take full advantage of that momentum.

What’s holding you back from making your move this spring? And what would help you feel ready? Connect with an agent to talk about it.

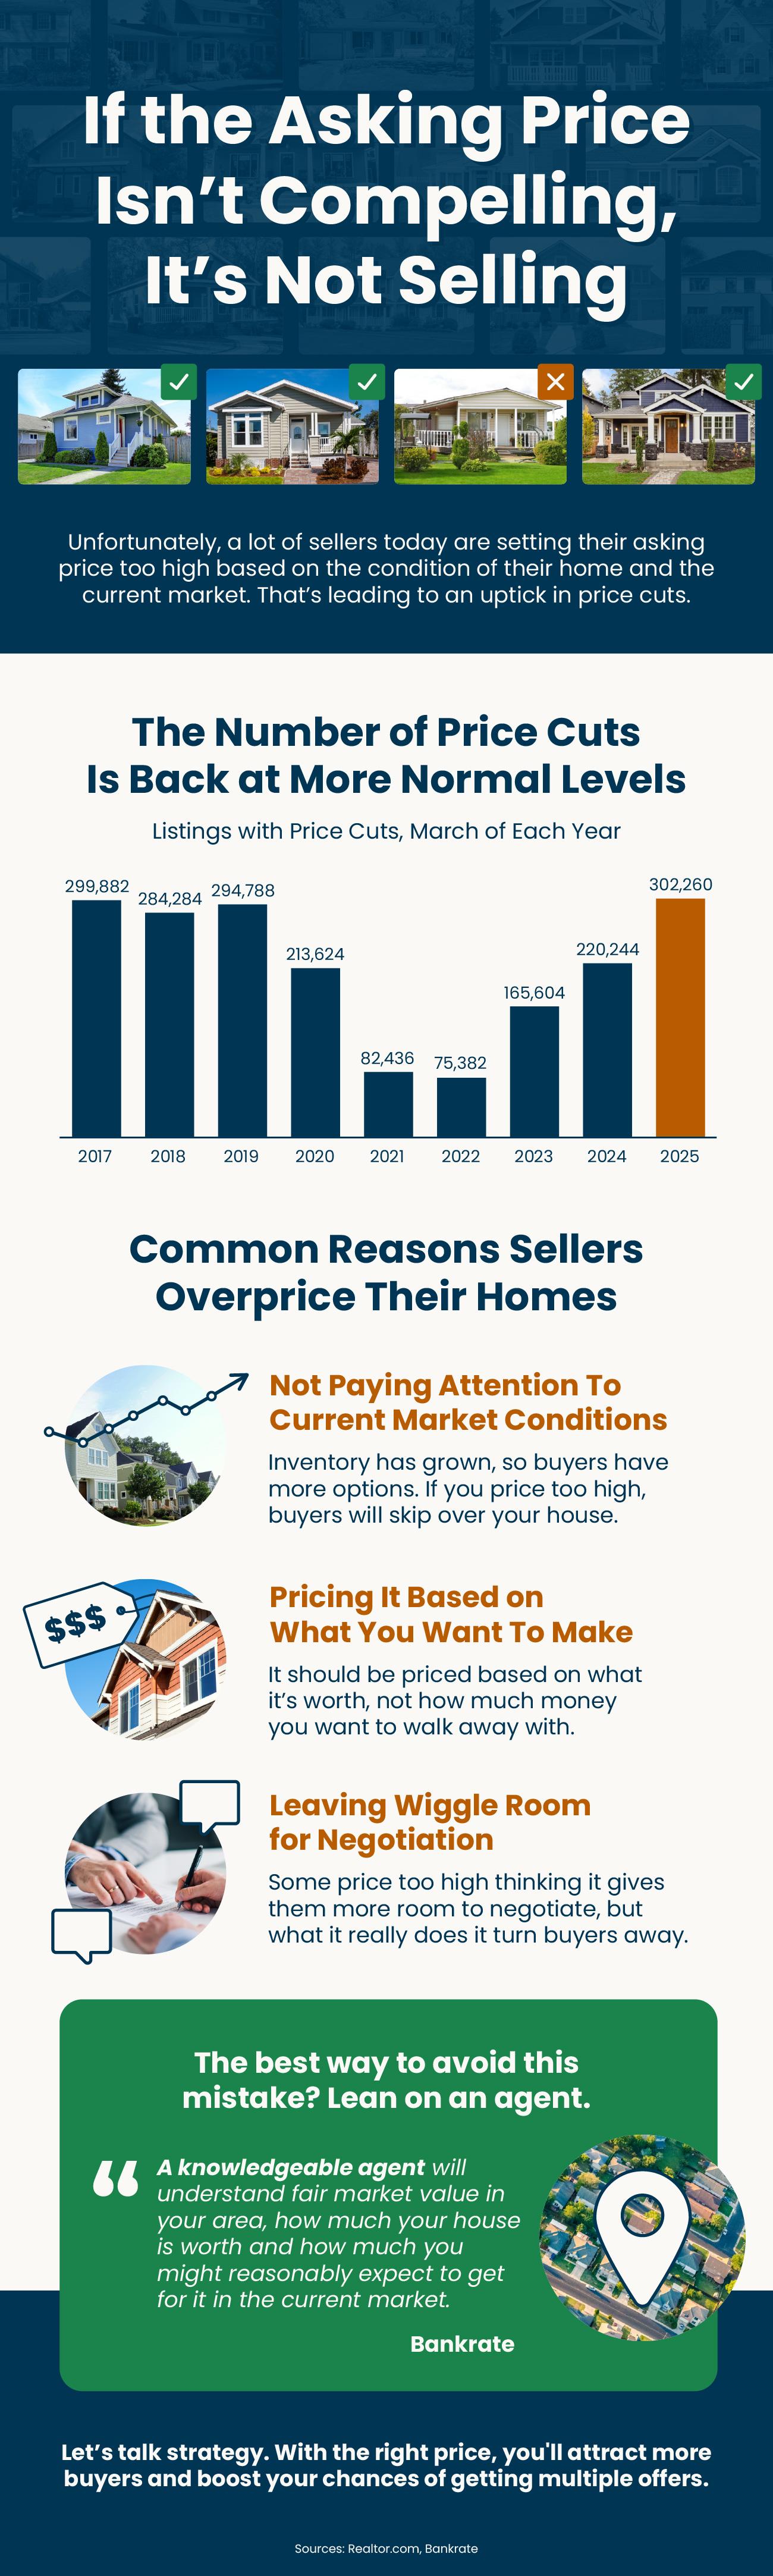
If the Asking Price Isn’t Compelling, It’s Not Selling

If the Asking Price Isn’t Compelling, It’s Not Selling Simplifying The Market

a screenshot of a phone

Some Highlights

  • Unfortunately, a lot of sellers today are setting their asking price too high. That’s leading to an uptick in price cuts.​
  • Some of the most common reasons this is happening are that they’re not paying attention to current market conditions or they’re trying to leave room for negotiation.
  • The best way to avoid this mistake? Connect with an agent to make sure your house is priced to pull people in, not push them away.